For a primary residence with a longer hold, a co-op typically offers a lower entry price and lower closing costs. For a buyer who needs financing flexibility, easier resale, or the option to sublet, a condo usually fits better. Condo buyers pay a mortgage recording tax and title insurance that most co-op buyers skip. Co-op buyers accept a board approval process and tighter restrictions in exchange for those savings.
TL;DR:
- Co-op purchases can save buyers thousands of dollars in closing costs by avoiding mortgage recording taxes and title insurance fees, especially on high-value properties.
- Condos generally offer more flexible subletting, quicker approval processes, and simpler renovation rules, making them more suitable for investors or those needing short-term flexibility.
- The approval process for co-ops involves thorough financial vetting and interviews, often requiring sizable down payments and significant post-closing liquidity, which can extend transaction timelines.
- Buyers should consider the impact of unit aggregation rules on transfer taxes, as combining units in co-ops can push sales into higher tax brackets, affecting overall costs.
- Precise planning of closing costs, understanding building reserve funds, and early qualification are critical to avoid delays, especially when dealing with LLCs, foreign buyers, or building-specific restrictions.
Table of Contents
- How co-ops and condos are owned and governed
- Detailed cost comparison for closing and monthly ownership
- What boards ask for and how approval timelines differ
- Loans, tax treatment, and transfer tax issues to plan around
- How lifestyle and resale prospects differ between the two
- A practical checklist before you make an offer
- A board president’s view on what actually slows deals down
- What most advice on this topic gets wrong
- Getting Manhattan-specific guidance before you commit
- Sources
- FAQ
How co-ops and condos are owned and governed
The legal structure is the real difference, and it drives almost everything else about the transaction. When you buy a co-op, you’re not buying real property. You’re buying shares in a corporation that owns the building, and those shares come with a proprietary lease that gives you the right to occupy your unit. A condo purchase transfers you a deed to a specific unit, plus an interest in the building’s common areas. That distinction is why the New York State Attorney General treats co-op purchases as securities transactions rather than pure real estate deals.

Governance follows the same split. Co-op boards typically hold broad discretion to approve or reject a buyer, a subtenant, or a renovation plan, and they rarely have to explain their reasoning. Condo boards usually hold a narrower right, most often a right of first refusal, which means they can buy the unit themselves instead of letting your sale close, but they can’t reject you outright the way a co-op board can.
Monthly charges reflect the same ownership logic:
- Co-op maintenance typically bundles the building’s underlying mortgage payment, staff wages, insurance, and your share of real estate taxes into one monthly fee.
- Condo common charges cover building operations and reserves, while you pay your own property taxes separately, often in quarterly installments.
- Co-op boards can restrict subletting and renovations more aggressively because they’re managing shared financial exposure, not just shared space.
- Condo owners generally answer to building rules for structural work but have more latitude to rent out or renovate their own unit.
Detailed cost comparison for closing and monthly ownership
The closing-cost gap between the two structures is the single biggest financial variable in a Manhattan purchase. Condo buyers using a mortgage pay a mortgage recording tax, which runs from 1.8% to 1.925% of the loan amount depending on size, plus title insurance premiums that co-op buyers typically don’t need at all. Because a co-op purchase involves a UCC-1 financing statement rather than a mortgage against real property, most co-op buyers avoid both costs entirely.
Co-op buyers commonly save a substantial amount in closing costs on a $1 million purchase, largely from skipping the mortgage recording tax and title insurance, according to closing-cost comparisons from NYC Paycheck Calculator. The exact figure depends on your loan size and lender fees, so ask for a line-item estimate before you bid.
Recurring costs matter just as much as closing day. A few things to check before you sign a contract:
- Confirm whether the maintenance or common charge figure already includes an upcoming assessment for capital repairs.
- Ask about the building’s reserve fund balance relative to its annual budget.
- Get the exact flip tax formula in writing, since co-op flip taxes (a resale fee some co-ops charge sellers, our closing-cost guide breaks these down) commonly run 1% to 3% of sale price and are rare in condos.
- Ask about move-in deposits, recognition agreement fees for lenders, and board application fees, which apply mostly to co-ops.
What boards ask for and how approval timelines differ
Co-op boards typically require a full board package: financial statements, tax returns, bank and reference letters, an employment letter, and a personal interview. Most Manhattan co-op boards expect 20% to 25% down and want to see meaningful post-closing liquidity, sometimes a full year or two of maintenance and mortgage payments held in reserve. Some buildings ask for more, particularly prewar co-ops with conservative boards, so check building-specific requirements early through your agent or our co-op buying guide.
Condo reviews move faster because the board is usually only exercising its right of first refusal, not vetting your finances the way a co-op board does. Waiver windows are typically shorter, often measured in days rather than the weeks a co-op interview and approval process can take.
A few steps consistently shorten approval time:
- Submit a complete, well-organized package the first time. Missing documents are the most common cause of delay.
- Get fully underwritten mortgage pre-approval before you submit, not just a pre-qualification letter.
- Ask your agent to request the building’s financials and minutes before you bid, so surprises don’t surface mid-review.
Pro Tip: A short cover letter summarizing your income, liquidity, and references, attached to the front of your package, often reduces a board’s follow-up questions.
Watch for red flags in the minutes and financials: repeated mentions of cash-flow shortfalls, a pattern of special assessments, or a sponsor that still controls a large block of unsold shares. Any of those can signal a building under financial stress.
Loans, tax treatment, and transfer tax issues to plan around
Because a co-op purchase uses a share loan rather than a real property mortgage, it isn’t subject to the mortgage recording tax that applies to condo financing, which is where much of the closing-cost savings mentioned earlier comes from.
Transfer tax rules get more complicated when multiple units are involved. NYC Department of Finance letter rulings show that when a buyer combines adjacent co-op units in a single transaction, the city can aggregate the consideration for real property transfer tax purposes, pushing the sale into a higher tax bracket than either unit would trigger alone.
A few things worth confirming before you sign anything:
- Ask whether your target purchase involves any unit combination, since that changes your transfer tax exposure.
- Confirm the building’s abatement status: the Cooperative and Condominium Property Tax Abatement is filed by the board or managing agent on behalf of the whole building, not by individual owners, with a filing deadline of February 15.
- If you’re buying through an LLC or as a foreign national, confirm eligibility for both financing and the abatement early, since primary-residency certification requirements can disqualify LLC-held or investment units.
How lifestyle and resale prospects differ between the two
Sublet policies are often the deciding factor for buyers who might need flexibility. Many co-op boards cap subletting at one or two years within a rolling period, and some prohibit it entirely after an initial ownership window. Condos generally allow owners to rent freely, which makes them the more practical choice for anyone who might need to relocate temporarily or hold the unit as an investment.
- Renovation approval in a co-op typically requires board sign-off on plans, contractor insurance certificates, and sometimes an engineer’s review.
- Condo renovations usually need building management approval for structural or system work but leave more day-to-day discretion to the owner.
- Manhattan’s buyer pool skews larger for condos, which tends to support faster resale and, according to market reporting from the New York Times, a higher price per square foot than comparable co-ops.
- A co-op’s lower entry cost is the tradeoff for a shallower resale market. If your hold period is short or uncertain, that tradeoff deserves real weight before you commit.
A practical checklist before you make an offer
Before you write an offer on either type of apartment, work through this list:
- Confirm your financing is realistic for the unit type, since co-op share loans and condo mortgages carry different underwriting standards.
- Calculate the full closing-cost delta between the two, including the mortgage recording tax if you’re financing a condo.
- Review the building’s sublet and renovation rules against your own likely timeline and plans.
- Request the last two years of board minutes and financial statements, plus the offering plan for a sponsor sale.
- Ask about the flip tax formula, if any, and who typically pays it.
Pro Tip: Ask your agent this exact question before bidding: “What does this specific board’s package require, and what’s the average approval timeline for this building?” Building-specific answers matter more than general rules.
If the purchase involves multiple units, an LLC, foreign ownership, or unclear abatement status, loop in a real estate attorney or tax advisor before you sign a contract, not after.
A board president’s view on what actually slows deals down
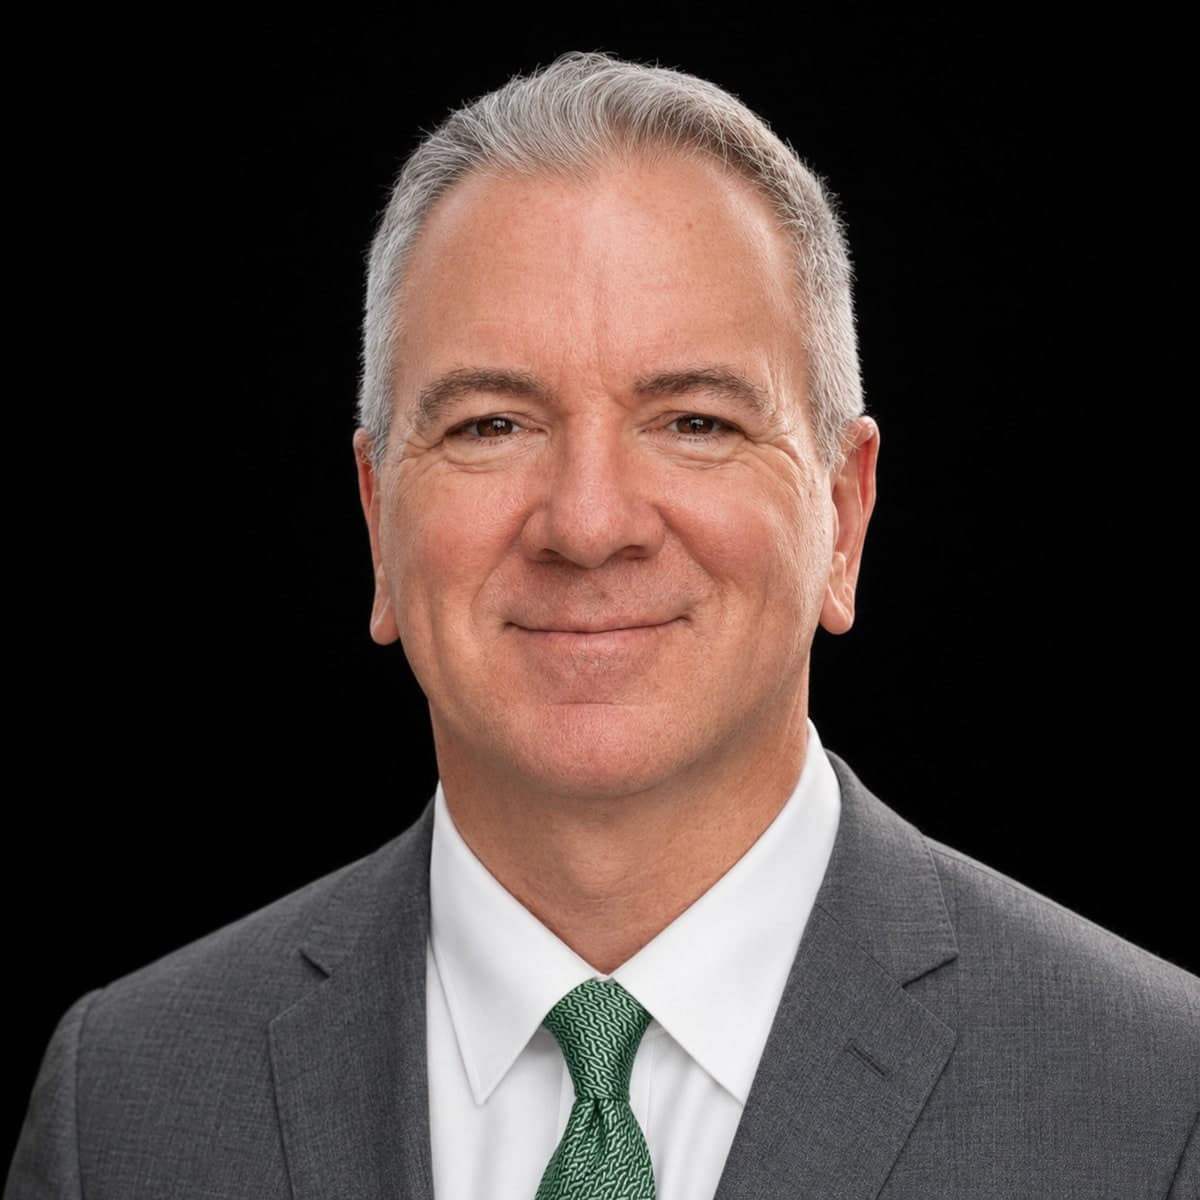
Michael J. Carroll is a licensed real estate salesperson with Brown Harris Stevens and has spent three decades working the Manhattan market, including time as a co-op board president on the Upper West Side. That board seat gives him a firsthand read on what actually gets a package approved quickly, and what stalls it.
The most common delay isn’t a weak financial profile. It’s an incomplete package, missing bank letters, unclear employment documentation, or a cover letter that doesn’t answer the questions a board is actually asking. Foreign buyers and LLC purchasers face extra scrutiny, which makes early, realistic closing-cost and eligibility planning especially valuable for those buyers.
What most advice on this topic gets wrong
Most co-op versus condo advice treats the choice as a simple tradeoff: co-op equals cheap and restrictive, condo equals expensive and free. That framing misses the part that actually costs buyers money, which is timing. A co-op’s savings on mortgage recording tax and title insurance are real, but they only pay off if you can also get through board approval without delay, and a disorganized package can eat those savings in carrying costs and lost negotiating leverage.
The other blind spot is transfer tax exposure on combined units. Buyers assume RPTT rates are fixed and flat, when in fact aggregation rules can push a two-unit co-op purchase into a materially higher bracket. That’s not a footnote. It changes the math on whether combining units is worth it at all.
My honest read: don’t choose based on sticker price alone. Choose based on your hold period, your tolerance for board scrutiny, and whether you’ve actually priced the closing costs specific to your loan size and building.
— Michael Carroll
Getting Manhattan-specific guidance before you commit
The article discusses common situations faced by Manhattan buyers navigating these decisions, including first-timers weighing co-op board packages, and foreign and LLC purchasers seeking realistic closing-cost projections before bidding.

- Board-package preparation and building financial review for co-op purchases.
- Line-item closing-cost planning so there are no surprises at the table.
- Neighborhood selection and negotiation support across Manhattan.
If you’re ready to start looking, visit the buying an apartment page to schedule a consultation.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Portal
- Buying a co-op or condo — NY State Attorney General
- NYC Dept. of Finance — Redacted letter ruling FLR-23-5030-RPTT
FAQ
Is it better to buy a condo or a co-op?
Neither is universally better. Condos tend to suit buyers who want financing flexibility, easier subletting, and faster resale, while co-ops often suit primary-residence buyers on a longer timeline who want lower closing costs, according to comparisons from NYC Paycheck Calculator.
What happens to a co-op when someone dies?
Co-op shares and the proprietary lease typically pass to the owner’s estate or named beneficiaries, similar to other personal property, though the board usually still has to approve the transfer to a new occupant or buyer. Executors should review the building’s bylaws and proprietary lease early, since some boards impose specific requirements on estate sales.
Why would someone want to live in a co-op?
Co-ops often cost less upfront because buyers typically skip the mortgage recording tax and title insurance that condo buyers pay, and monthly maintenance usually folds in the building’s real estate taxes. Many buyers also value the closer-knit governance and financial oversight that comes with board-run buildings.
What is the downside of a co-op?
The board approval process can be lengthy and intrusive, requiring detailed financial disclosure, references, and often an in-person interview with no guarantee of approval. Co-ops also tend to restrict subletting and renovations more tightly than condos, and their resale market in Manhattan is generally narrower than the condo market.