Plan for approximately 4 to 6 percent of the purchase price for a financed condo. The largest items are the mansion tax on purchases of $1 million and up, a mortgage recording tax near 1.925 percent of the loan, and title insurance of about $4 per $1,000 of price. Add attorney fees, bank and appraisal fees, and prepaid common-charge and tax adjustments. Confirm current rates with your attorney.
The condo buyer's guide
Buying a condo, the flexible way to own in New York.
Buying a condo means owning your apartment outright by deed, with no board approval to pass — only a right of first refusal the board almost never uses. Condos cost more than co-ops but offer flexibility: foreign buyers, LLCs, pied-a-terre use, and subletting are all welcome, though since July 2026 a second home the city values at $1 million or more carries an annual pied-à-terre surcharge. Expect to close in about two to three months.
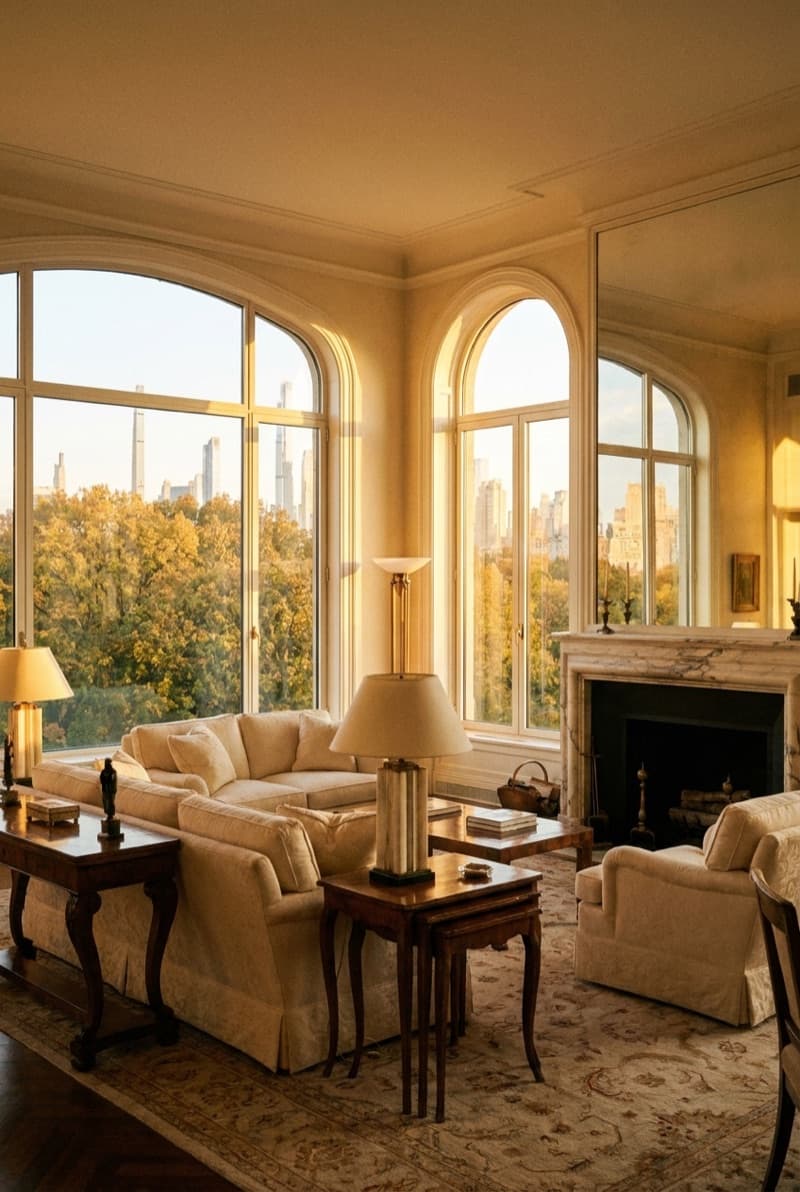
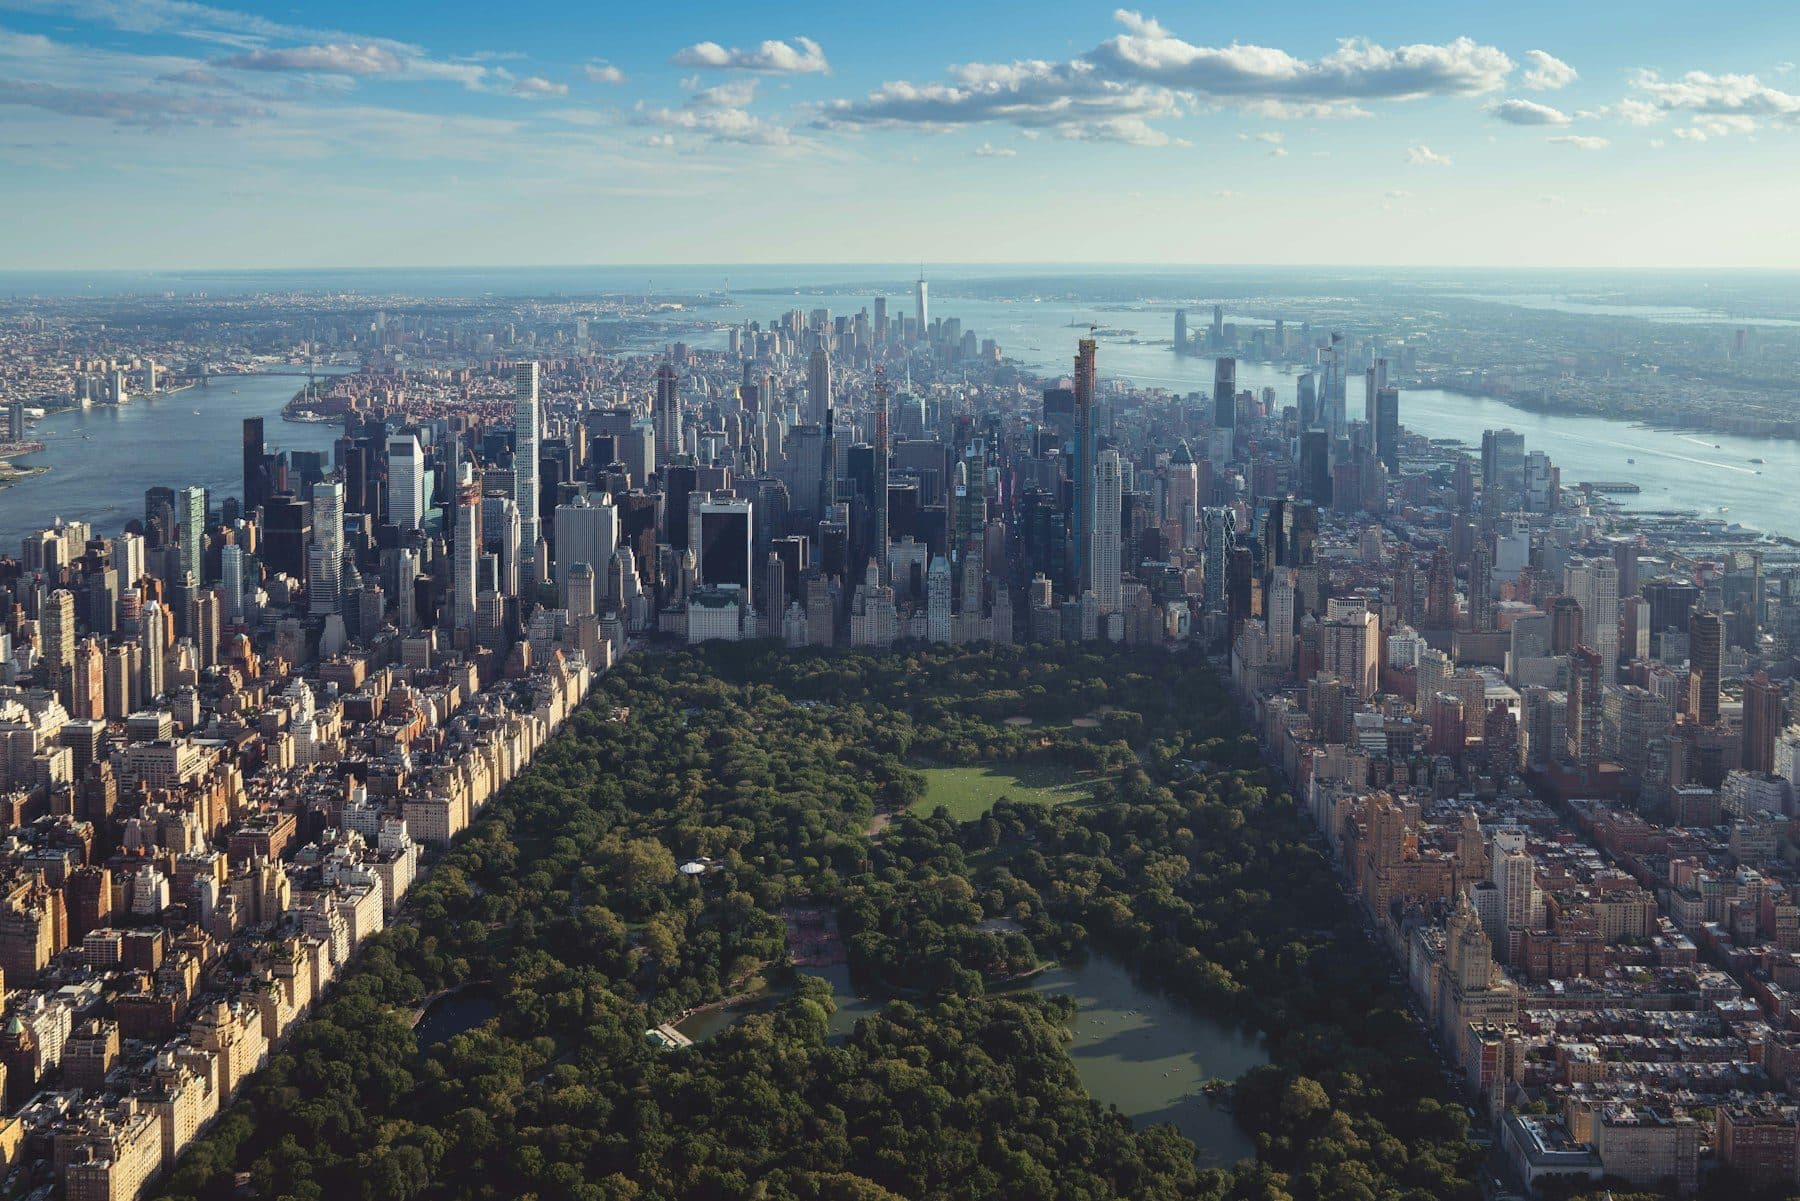
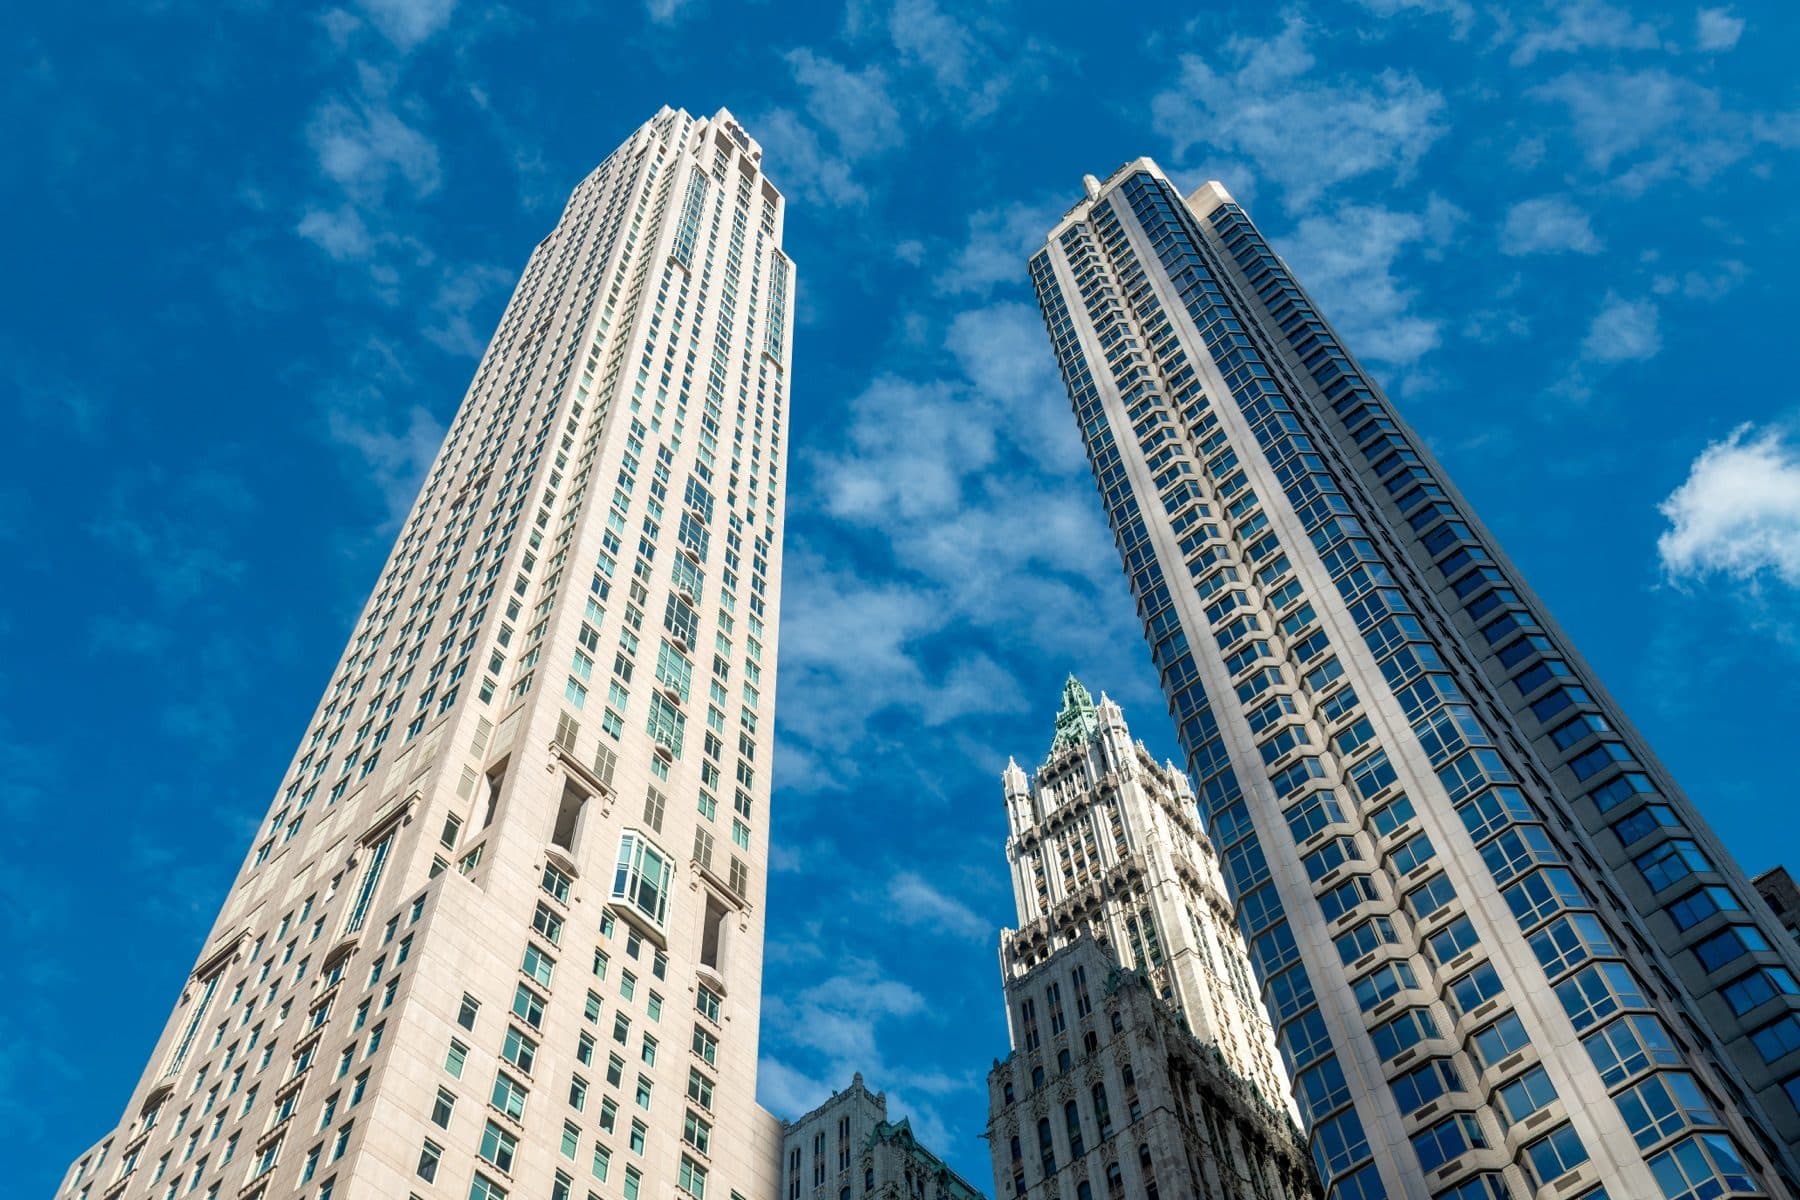
A Central Park West condominium
How does buying a condo in NYC work, step by step?
You make an offer, sign a contract with a deposit of customarily 10 percent, and secure financing if you need it. Instead of a co-op board interview, the condo board simply exercises or waives its right of first refusal — which almost always means waiving. Then you close. Because there is no board approval to clear, a condo usually closes in about two to three months, faster than a co-op.
A condo purchase has fewer moving parts than a co-op, but the details still matter — the offering plan, the building's financials, and the house rules all shape what you are actually buying. Michael reads each one closely, so the “easier” purchase does not hide a costly surprise.
What you pay to close
A condo's closing costs, itemized.
A financed condo carries a mortgage recording tax and title insurance that a co-op avoids, so its closing costs run higher. Michael builds the real number with you before you offer — no rosy estimate.
Typical ranges, not a quote. Your figures depend on price, financing, and the building — and rates change, so confirm with your attorney. For a full breakdown, see NYC closing costs explained.
- Mansion tax1%+ at $1M and up
- Mortgage recording tax (financed)≈ 1.925% of the loan
- Title insurance≈ $4 per $1,000 of price
- Bank, appraisal & application fees$1,500–$3,000
- Typical all-in, financed condo≈ 4–6% of price
Why do condos cost more than co-ops?
Condos carry a premium for flexibility and an easier purchase. You own real property by deed, there is no board approval to pass, foreign buyers and LLCs are welcome, subletting is usually allowed, and financing is simpler. In Manhattan the condo median sits near $1.75 million against a co-op median near $850,000 — one of the widest gaps in years.
The premium buys you options. If you might sublet, buy through an entity, use the apartment part of the year, or expect to move, a condo protects that flexibility in a way most co-ops will not. Weighing that against the price is exactly the conversation Michael has with you, against specific buildings rather than in the abstract.
Flexibility, at a premium
Open to buyers from anywhere
Can a foreign buyer, an LLC, or an investor buy a condo?
Yes — condos are the natural fit. They welcome foreign buyers, LLCs, trusts, pied-a-terre use, and investors with far fewer restrictions than co-ops. There is no board interview and, in most buildings, no primary-residence requirement, and subletting is generally permitted. One new line in the budget: since July 1, 2026, an apartment that is not your primary residence owes New York's annual pied-à-terre surcharge once the city values it at $1 million or more. If you are buying through an entity, or the apartment will not be your primary residence, a condo is almost always the path whose rules fit.
Nothing wastes more time than chasing buildings whose written rules will never fit your purchase. Michael reads each building's requirements first — who may hold title, primary-residence rules, sublet policy — and builds your search around the condos and new developments whose rules fit, so it rests on buildings that can actually say yes.
Own it outright, by deed
What should I know about buying a new-development condo?
In a sponsor sale, the buyer often absorbs costs a resale buyer would not: the sponsor's New York City and State transfer taxes, the sponsor's attorney fee, a working-capital contribution of roughly one to two months of common charges, and sometimes a share of the resident manager's unit. These are negotiable and meaningfully change the true cost.
New construction is exciting, but the sponsor's contract is written to protect the sponsor. Michael reads the offering plan closely, models the real all-in cost including the transfer taxes you may be asked to cover, and negotiates the terms that are actually on the table.
Two more questions belong on the list. Does the building carry a tax abatement, and when does it step down? The 421-a program closed to new projects in 2022 but still runs in buildings that qualified, and 485-x has replaced it for newer ones; either way, ask for the unabated tax figure and the year it arrives. And if you agree to pay the sponsor's transfer taxes, that amount is added to the price when the mansion tax is calculated, which can push a deal over a bracket line.
New development, from the ground up
“A condo hands you the keys with fewer hurdles. My job is to make sure fewer hurdles never means fewer questions asked.”
— Michael J. Carroll
Answers
Buying a condo, answered
- It is the condo board's option to step in and buy the apartment on the same terms you have negotiated, rather than approving or rejecting you as a buyer. In practice boards almost never exercise it. The board reviews your completed application and issues a waiver, usually within about 20 to 30 days. A condo board generally cannot decline a qualified buyer the way a co-op board can.
- Common charges are your monthly contribution to running the building — staff, maintenance of common areas, amenities, and reserves — paid to the condo's board of managers. Unlike a co-op's maintenance, they do not include your real estate taxes, which you pay separately to the city. Common charges are generally lower than a comparable co-op's maintenance, but remember to budget the property taxes on top.
- About two to three months from accepted offer to closing, and faster for an all-cash purchase. The main variables are your financing and the board's turnaround on the right of first refusal, which typically runs 20 to 30 days. Without a board package and interview, a condo moves more quickly than a co-op.
A private consultation
Ask Michael about a condo
Weighing a specific condo, a new development, or whether a condo or co-op fits you better? Send Michael the details and he will give you a straight read — on cost, flexibility, and the building — before you commit.
What happens next
- 01
Michael reads your note personally
No team inbox. He sees the form himself.
- 02
You'll hear back, usually the same day
By phone or email — whichever you prefer.
- 03
A no-pressure first conversation
Whether you're ready this week or thinking it through.
10+
Years at BHS
Top 1%
Nationwide
$500K–$25M+
Transaction range
Tell Michael about your search
A few quick questions.
Your details stay between you and Michael. No spam. No list.