No. Co-ops are about three quarters of Manhattan apartments and include many of the city's most sought-after pre-war homes. They usually cost less per square foot and the board screening keeps neighbors financially sound. The trade is flexibility: stricter approval, financing caps, and limits on subletting and resale. For a primary home, that structure often works in your favor.
The first decision
Apartment or co-op? Start here.
An apartment you own outright, what most of the country calls a condo, is real property with no board approval, which is why condos cost more and suit foreign buyers, LLCs, and flexibility. A co-op means owning shares in the corporation that owns the building, requires board approval, and usually costs less but restricts subletting and resale.
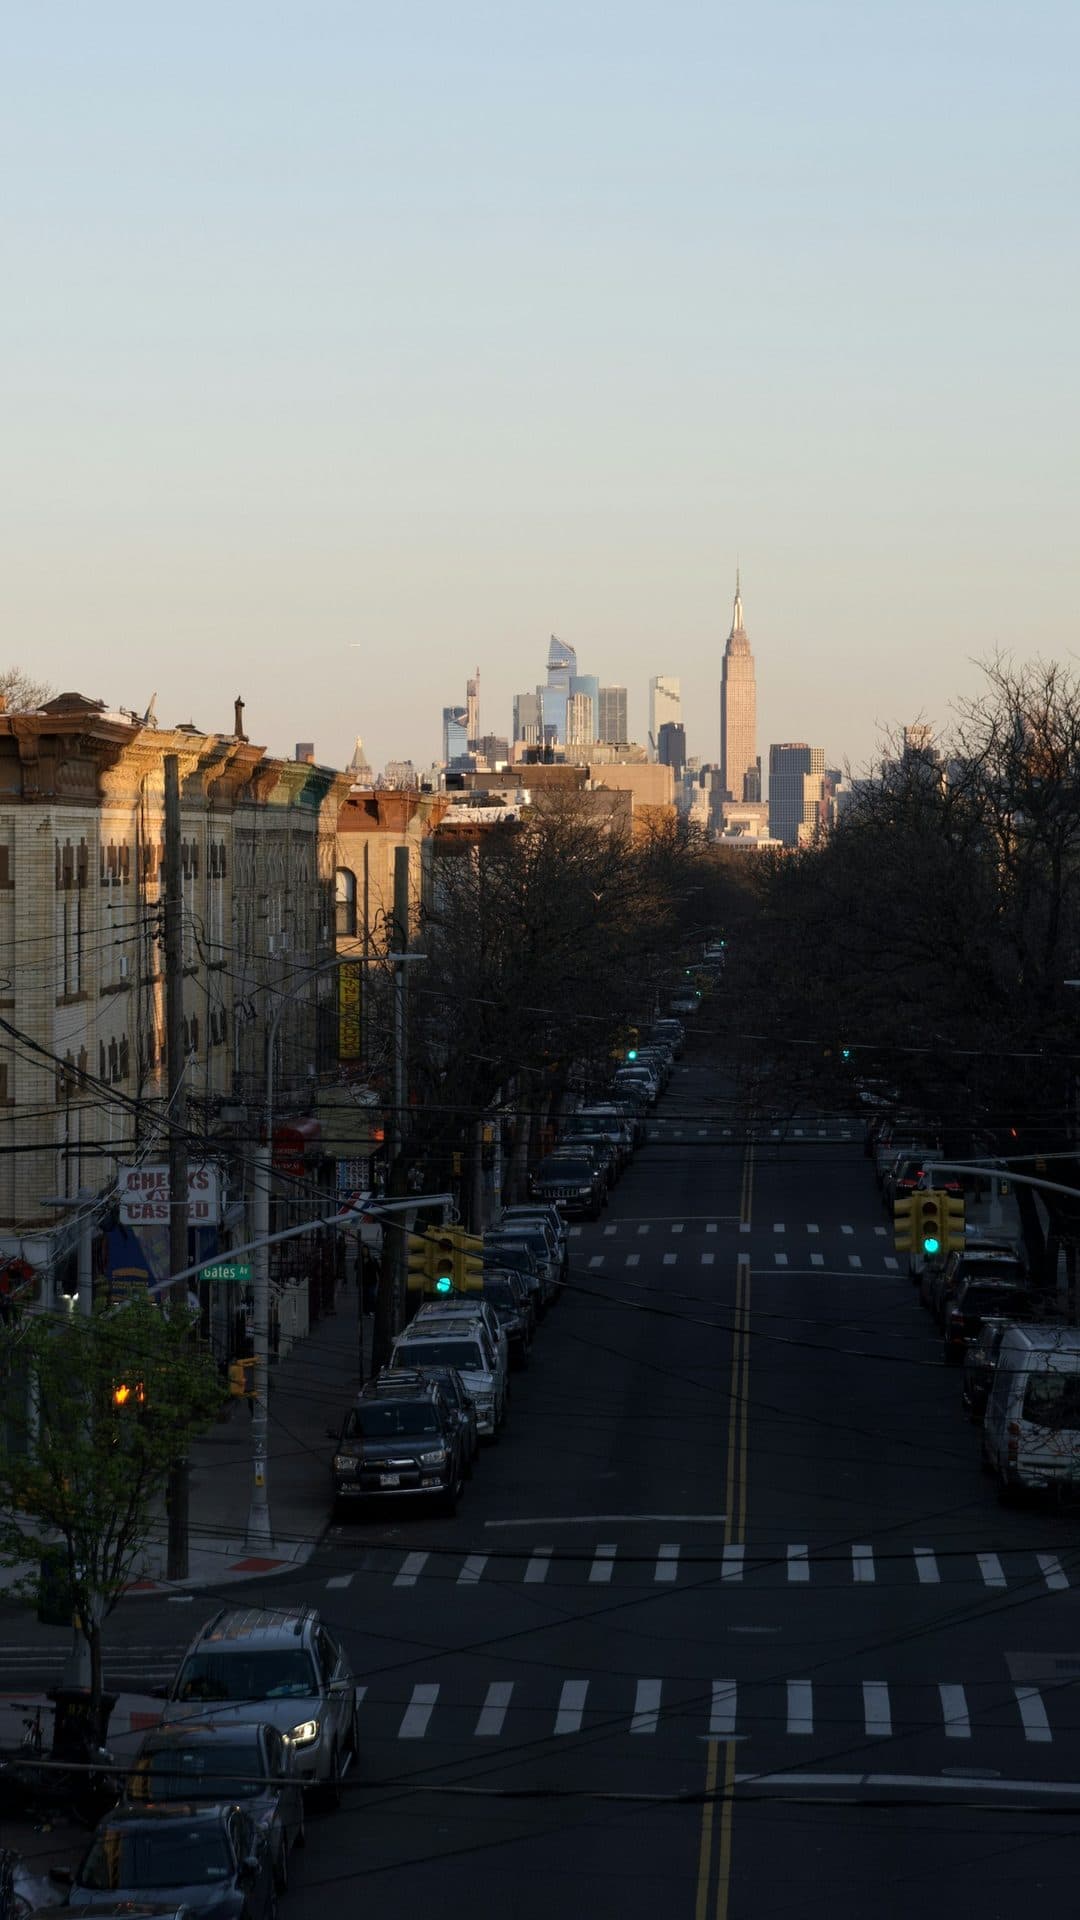
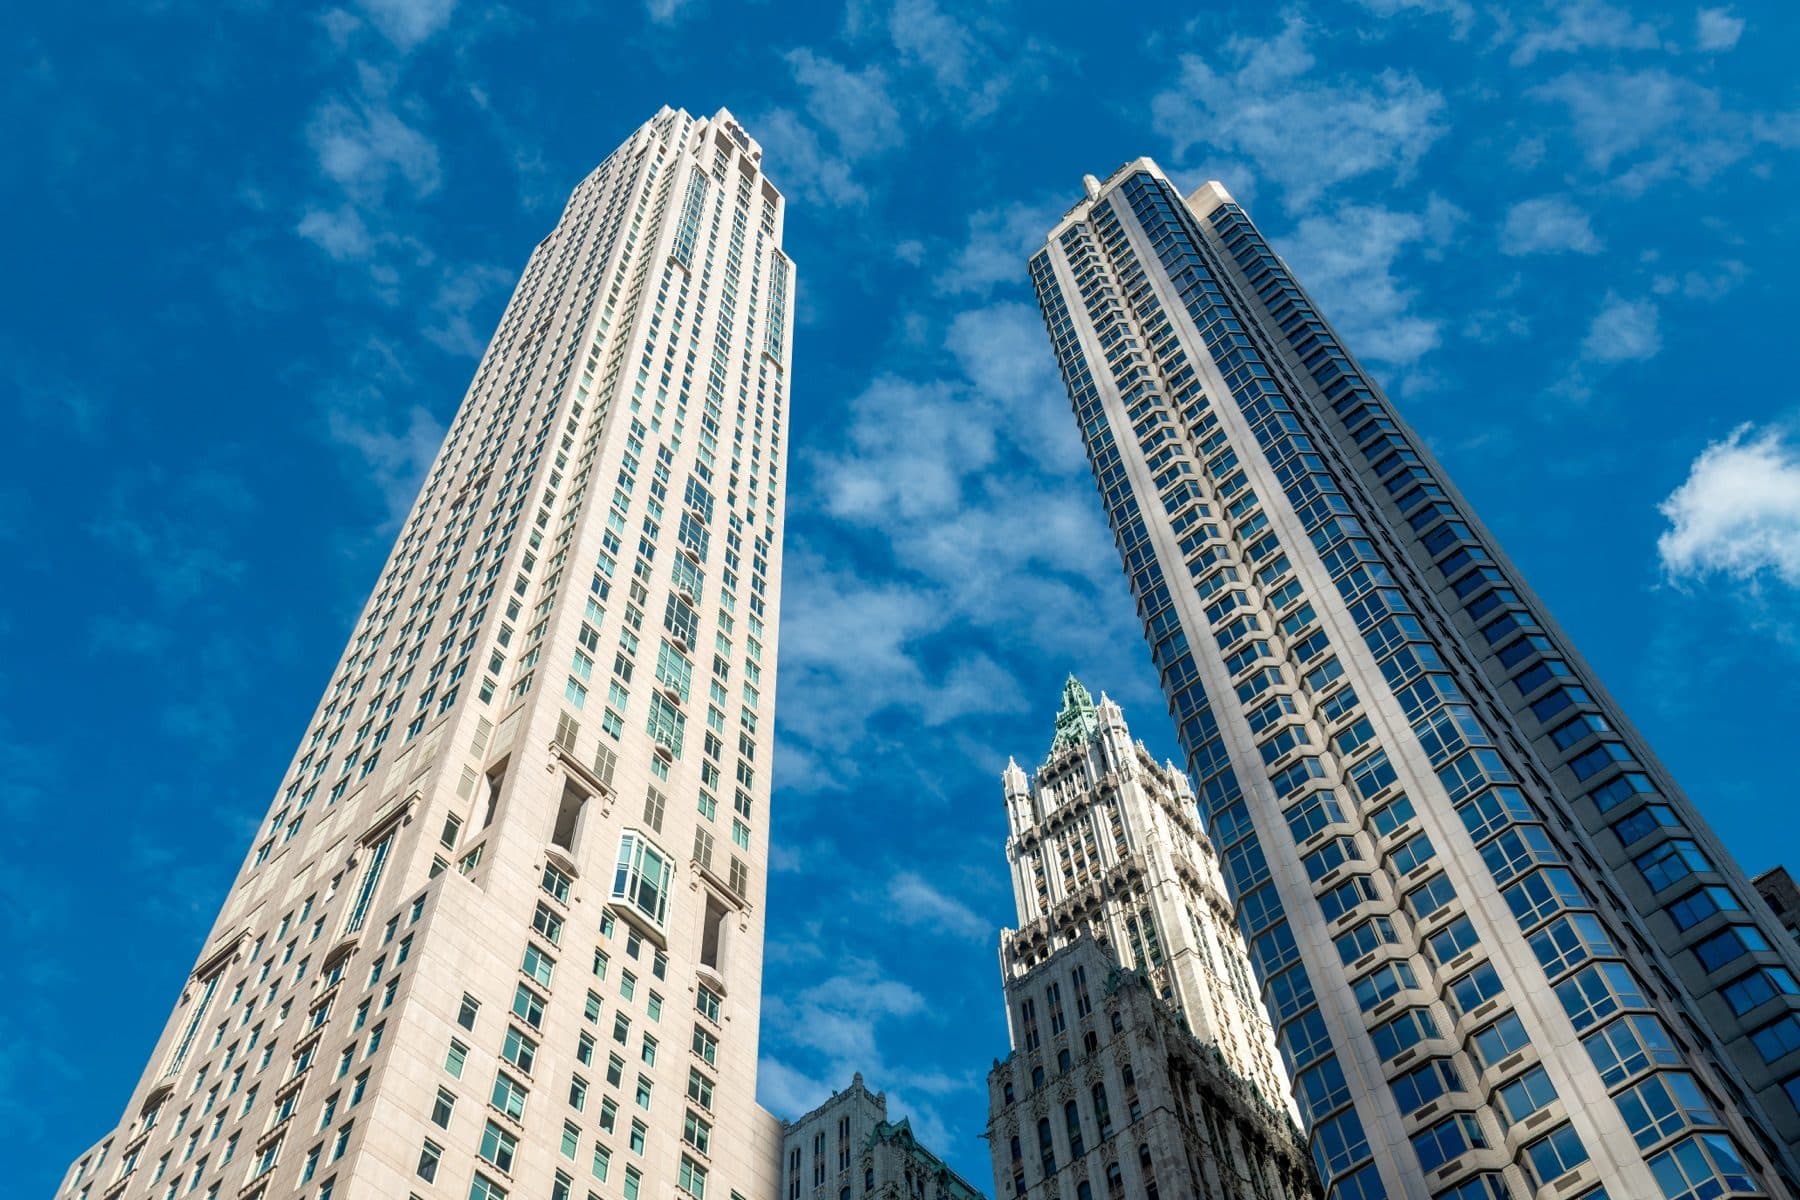
Modern condo towers
What is the real difference between a condo and a co-op?
A condo is real property. You own your apartment by deed, the way you own a house. A co-op is a corporation that owns the building, and you own shares plus a proprietary lease for your apartment. That one legal difference drives price, approval, financing, and who is even allowed to buy.
Everything buyers weigh between the two comes back to this. With a condo you hold a deed to real estate. With a co-op you hold shares and a lease. It sounds technical, but it explains why one costs more, why one requires a board interview, and why one welcomes an LLC while the other usually will not.
Side by side
Condo vs co-op, at a glance.
The nine differences that actually shape your decision — what you own, what you pay, and who will say yes to you.
Condo
Flexibility & freedom
Real property you own by deed. No board approval. Welcomes foreign buyers, LLCs, and investors. Higher price, simpler purchase.
Co-op
Value & community
Shares plus a proprietary lease. Board approval required. Usually a lower price, restricted subletting, stable owner-occupied buildings — about three quarters of Manhattan.
What it meansCondoCo-op
What you own
Real property, by deed
Shares in a corporation + a proprietary lease
Board approval
No — right of first refusal only
Yes — full board interview + package
Median price (Manhattan)
≈ $1.75M
≈ $850K
Down payment
10–20% common
20–30% common (sometimes 40–50%)
Mortgage recording tax
Yes — ~1.8–1.925%
None
Title insurance
Yes — ~0.4%
None
Foreign buyer / LLC
Usually welcome
Usually restricted
Subletting
Usually allowed
Usually restricted
Flip tax (seller)
Rare
Often 1–3%
Why do condos cost more than co-ops?
Condos carry a premium for flexibility and an easier purchase: no board approval, foreign buyers and LLCs welcome, subletting usually allowed, and simpler financing. In Manhattan the condo median sits near $1.75 million against a co-op median near $850,000, one of the widest gaps in years.
You are paying for freedom and ease. A condo lets you buy through an entity, rent the apartment out, and sell to almost any qualified buyer. That liquidity and flexibility command a higher price. A co-op asks more of you and gives you less flexibility, and the lower price reflects that trade.
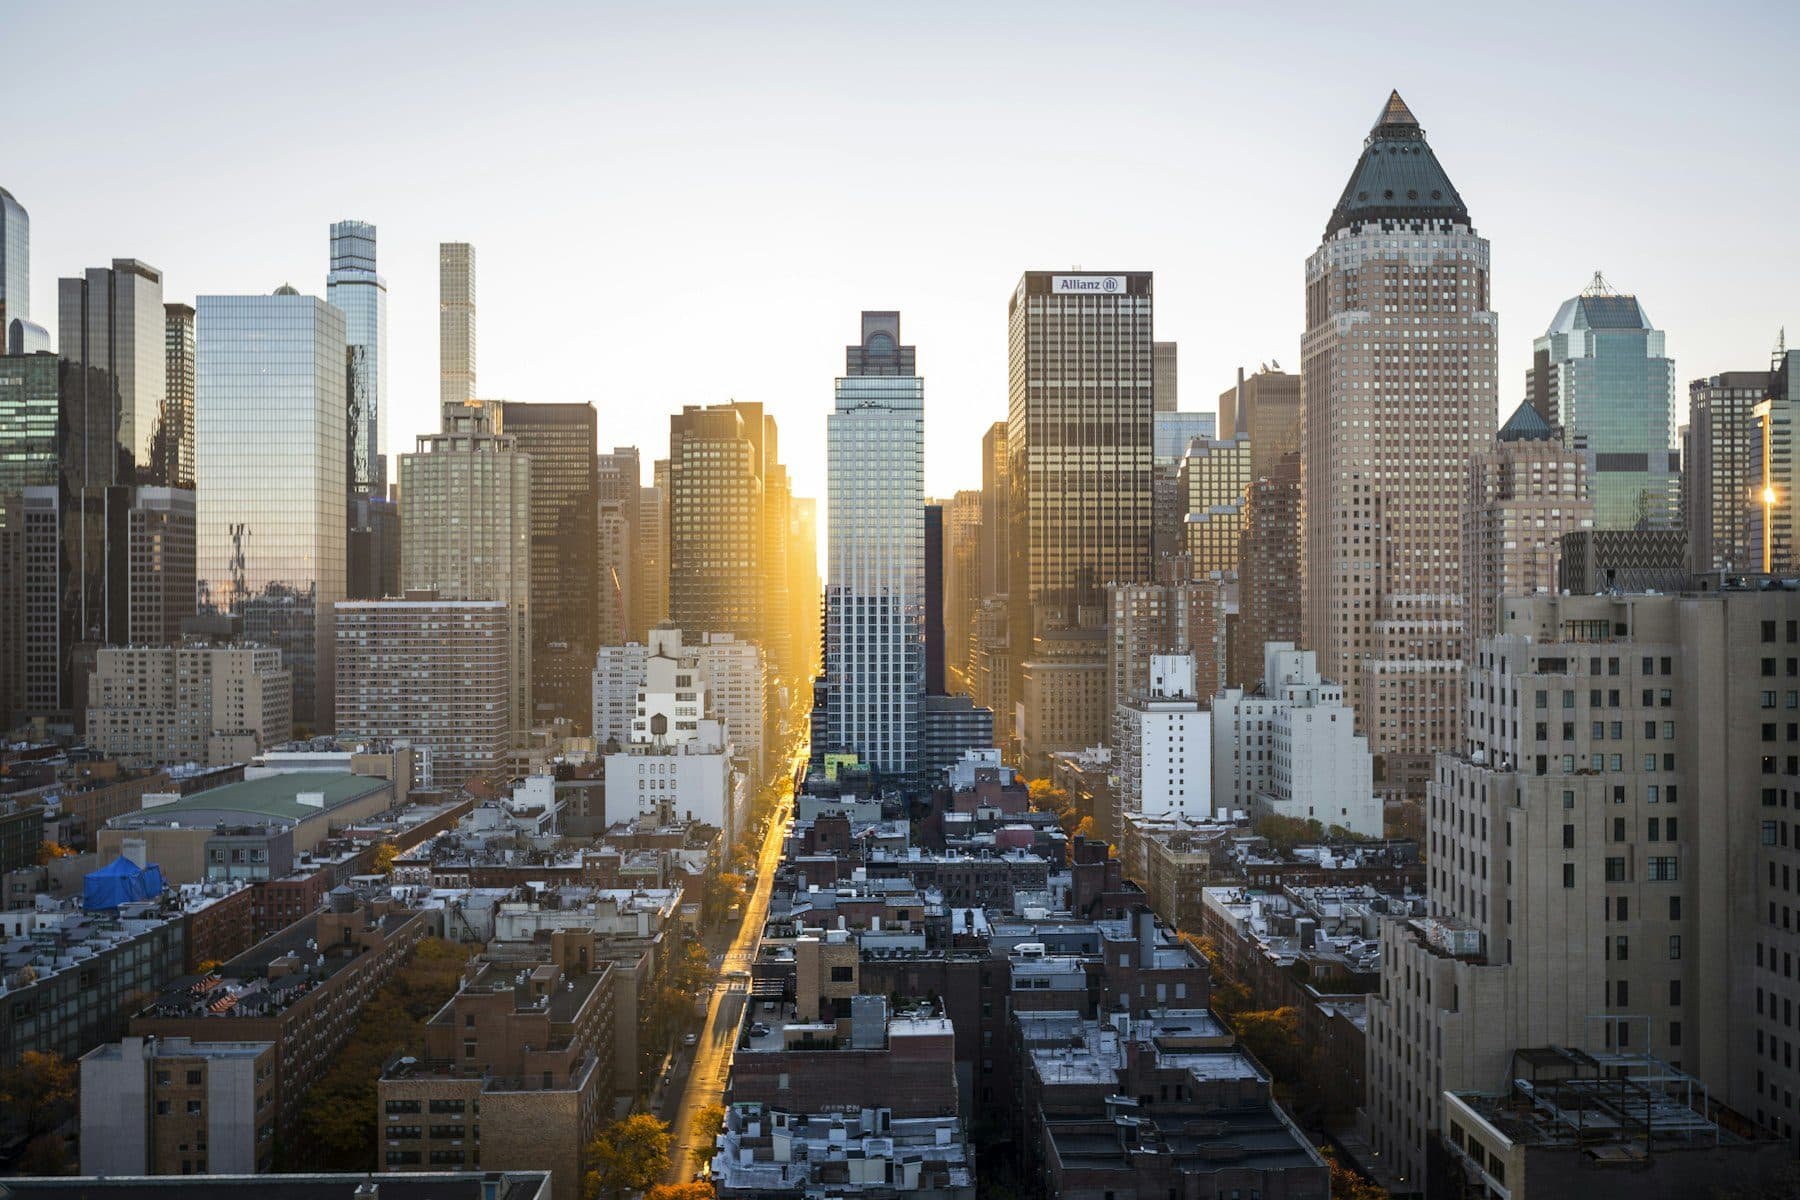
A new Manhattan condo at night
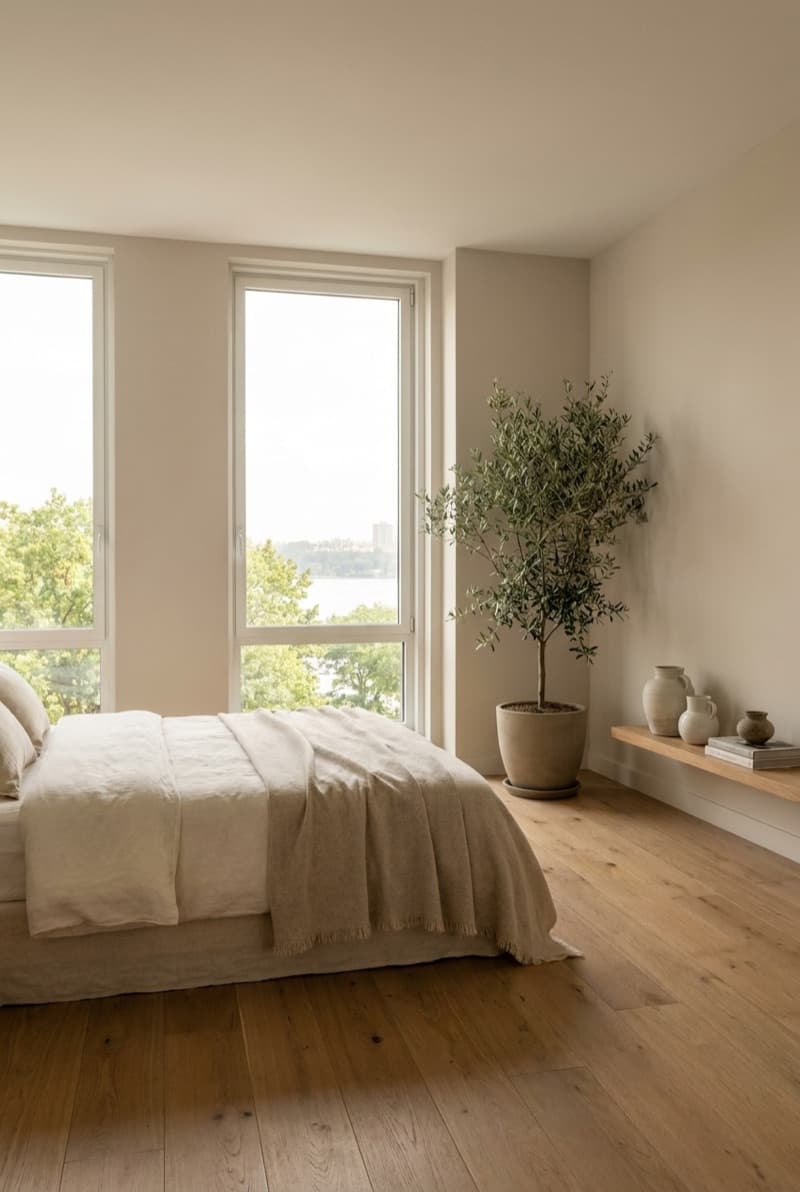
A light-filled two bedroom
Which costs less to close on, a condo or a co-op?
A co-op. Because a co-op purchase is shares rather than real property, buyers avoid the mortgage recording tax and title insurance that condos require. The buyer's mansion tax still applies to either at $1 million and up. Lower closing costs are one more reason budget-conscious buyers look hard at co-ops.
On a financed condo, the mortgage recording tax alone runs close to 1.9 percent of the loan, and title insurance adds more. A co-op skips both. The mansion tax, paid by the buyer on purchases of $1 million or more, applies to either. Confirm current rates with your attorney before you budget, since tax figures change.
Which is better if you are buying a home to live in?
Either can be right. A co-op can give you more space and a stable, owner-occupied building for less money if your finances are strong and you plan to stay. A condo gives flexibility if you might sublet, buy through an entity, or expect to move sooner. The building matters as much as the type.
The honest answer is that it depends on your finances, your timeline, and the specific building. Michael walks clients through both, then points them toward the homes where they will actually be approved and happy. That is a conversation worth having before you fall for an apartment.
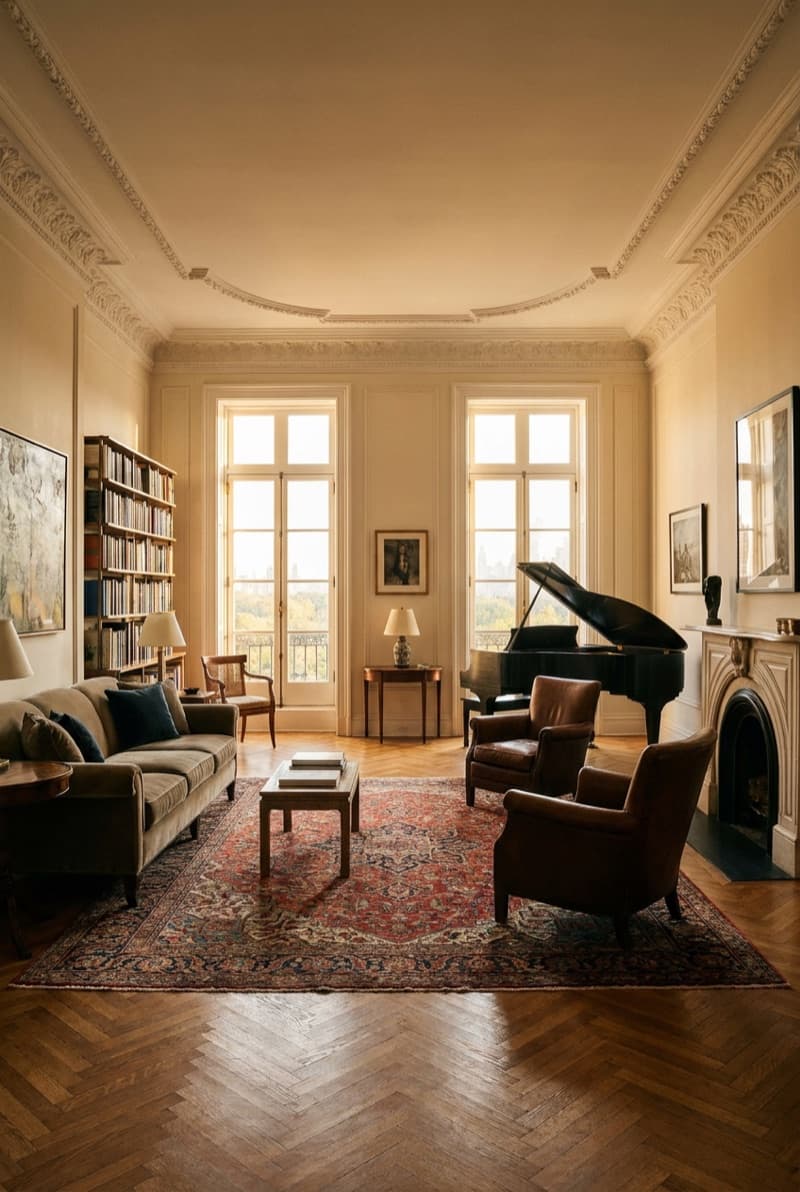
A classic seven
“The condo-or-co-op question is the wrong one. The right question is which building, of either kind, fits you — and will say yes.”
— Michael J. Carroll
Answers
Condo vs co-op, answered
- Yes, condos have boards, but they hold far less power over a sale. A condo board generally cannot reject a qualified buyer. It has a right of first refusal, meaning it can step in to buy the apartment on the same terms, which almost never happens. A co-op board, by contrast, can approve or deny any buyer.
- Condos generally allow subletting with few restrictions, which is why investors prefer them. Most co-ops restrict subletting sharply, often allowing it only after you have lived there a few years and then only for a limited period. If renting your apartment out matters to you, that usually points toward a condo.
- You submit a detailed package: tax returns, bank and brokerage statements, reference letters, and a financial summary. The board reviews it, then interviews you. They are checking that you can comfortably afford the apartment and will be a responsible shareholder. Michael prepares you so the package is clean and the interview holds no surprises.
A private consultation
Talk it through with Michael
Tell Michael about your finances and what you are looking for, and he will tell you honestly whether a condo or a co-op fits, and which buildings to look at first.
What happens next
- 01
Michael reads your note personally
No team inbox. He sees the form himself.
- 02
You'll hear back, usually the same day
By phone or email — whichever you prefer.
- 03
A no-pressure first conversation
Whether you're ready this week or thinking it through.
10+
Years at BHS
Top 1%
Nationwide
$500K–$25M+
Transaction range
Tell Michael about your search
A few quick questions.
Your details stay between you and Michael. No spam. No list.